Liquidity is a cornerstone concept in financial markets, representing the ease with which an asset can be bought or sold without causing a significant change in its price. In cryptocurrency markets, liquidity dynamics exhibit unique characteristics due to market structure, technology, and participant behaviour. This article offers a comprehensive examination of crypto liquidity, detailing its mechanisms, challenges, and practical implications for traders and investors.
Defining Liquidity in Crypto
Liquidity in crypto markets refers to the ability to execute transactions quickly and at predictable prices. It depends on the availability of counterparties willing to buy or sell assets at various price levels. Unlike traditional markets, crypto liquidity is fragmented across numerous exchanges and on-chain venues, each with distinct order books and trading pairs.
Order-Book Depth and Bid-Ask Spread
The order book is a real-time list of buy (bid) and sell (ask) orders at different price levels. Order-book depth measures the cumulative volume available at or near the current market price. A deep order book indicates high liquidity, allowing large trades with minimal price impact.
The bid-ask spread is the difference between the highest bid price and the lowest ask price. Narrow spreads typically signal robust liquidity and efficient price discovery. Conversely, wide spreads suggest lower liquidity and higher transaction costs.
Volume versus Liquidity
Trading volume, the total quantity of assets traded over a period, is often conflated with liquidity but is not synonymous. High volume can coincide with low liquidity if trades are concentrated in small price ranges or if the order book is shallow. Conversely, a market with moderate volume but deep order books may offer better liquidity conditions.
Order Types and Execution Nuances
Market and Limit Orders
Market orders execute immediately at the best available price, consuming liquidity from the order book. They are subject to slippage if the order size exceeds available volume at the top price levels.
Limit orders specify a price at which the trader is willing to buy or sell, adding liquidity by populating the order book. They may remain unfilled if the market price does not reach the limit price.
Partial Fills and Slippage
Large market orders may be partially filled across multiple price levels, increasing the effective execution price and causing slippage. Slippage quantifies the difference between the expected execution price and the actual fill price, often exacerbated in low-liquidity conditions.
Market Impact and Fragmentation
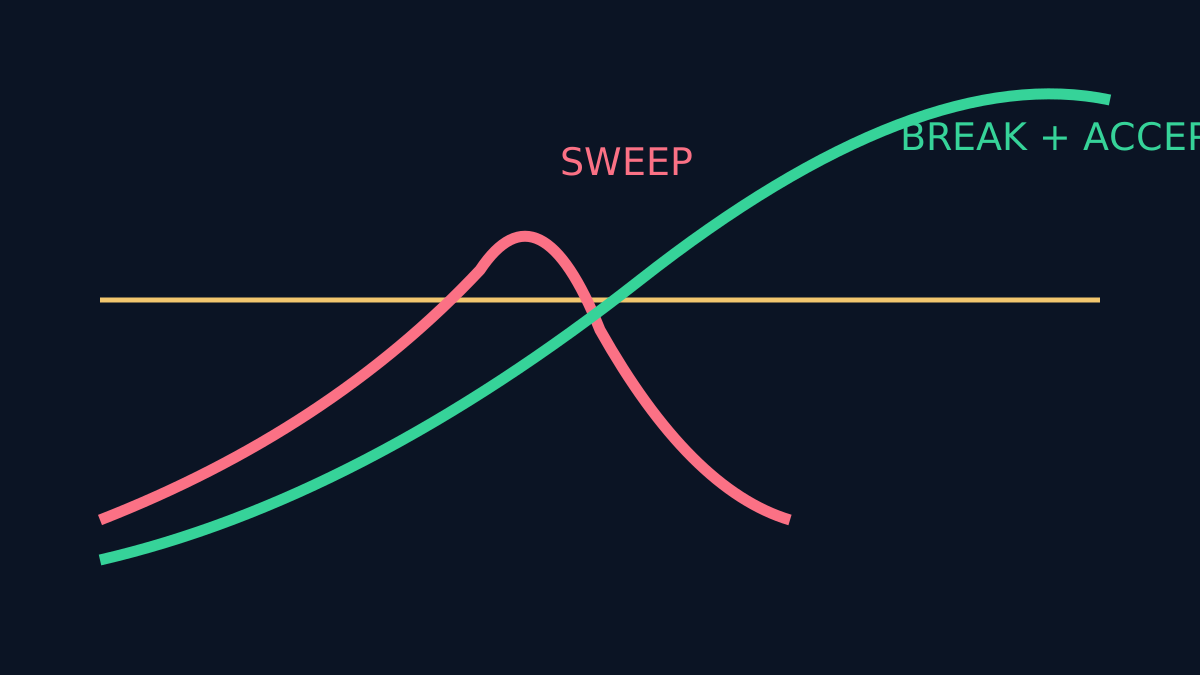
Executing large orders can move market prices, a phenomenon known as market impact. Traders must consider this when placing sizable trades, as aggressive orders can trigger adverse price movements.
Crypto liquidity is fragmented across centralized exchanges (CEXs), decentralized exchanges (DEXs), and on-chain liquidity pools. This fragmentation leads to disparities in prices, spreads, and available volumes across venues and trading pairs.
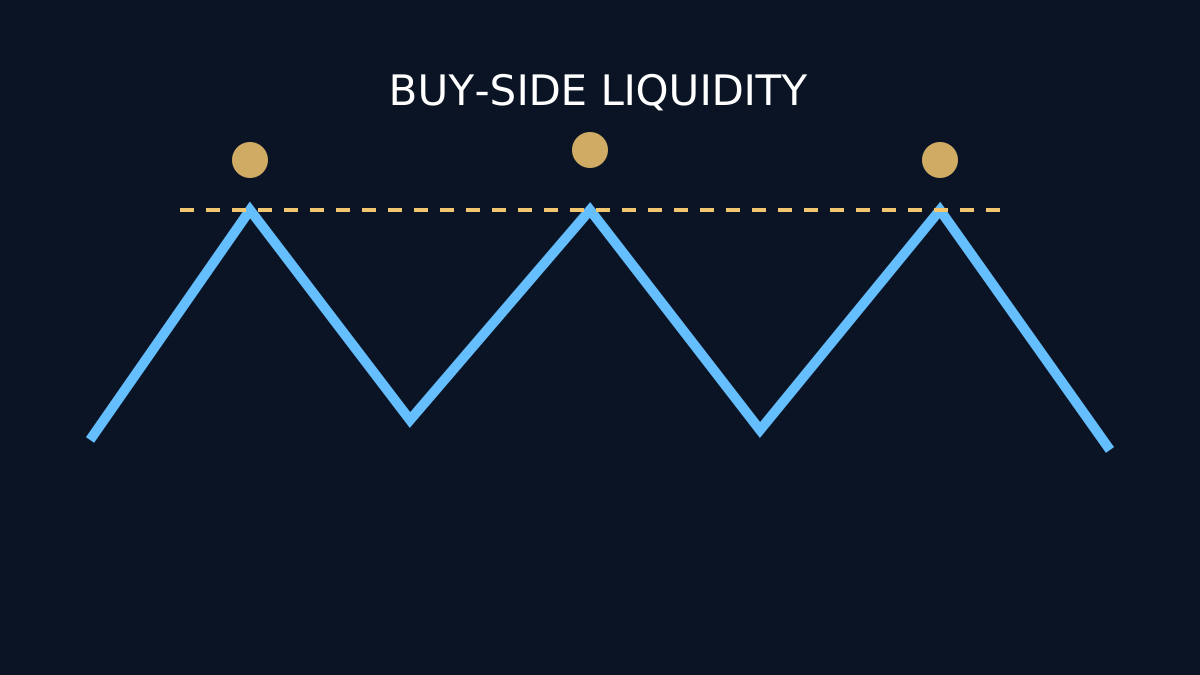
Understanding these differences is crucial for optimal trade execution and risk management.
Temporal and Operational Considerations
Weekends, Quiet Periods, and Volatility Feedback
Crypto markets operate 24/7, but liquidity can vary significantly during weekends or low-activity periods. Reduced participation often leads to wider spreads and increased volatility, creating feedback loops where price swings further deter liquidity providers.
Outages and API Risks
Technical risks such as exchange outages or API failures can abruptly reduce accessible liquidity, impairing order execution. Traders relying on automated strategies must incorporate safeguards against such disruptions.
Worked Examples of Execution
Consider a trader aiming to sell 10 BTC on a mid-sized exchange. The order book shows 2 BTC available at the best bid price, 3 BTC at the next level, and 5 BTC at a deeper level. A market order would consume these layers sequentially, potentially pushing the average execution price lower than the initial bid, illustrating slippage and market impact.
Alternatively, placing a limit order at the current best bid adds liquidity but risks non-execution if the market price falls.
Common Pitfalls and Misconceptions
- Equating volume with liquidity without considering order book depth.
- Ignoring fragmentation and assuming uniform prices across venues.
- Underestimating slippage and market impact in large orders.
- Overlooking operational risks such as outages or API latency.
Key Takeaways
For further reading on related topics, see Understanding Order Books and Slippage and Execution Risk.